With about 100 days remaining in the year, it is natural to pause and consider everything that has changed since January. Perhaps you have reached a personal goal, taken on a new responsibility, or made a major purchase. Looking back can be meaningful, but it is also a useful time to consider whether your insurance has changed along with your life.
Purchasing a home or vehicle, expanding your family, advancing in your career, or building assets are important milestones. They may also affect the protection you need. When policies are not reviewed after major changes, gaps in coverage can develop without being immediately obvious.
A year-end insurance review with Kim Osman Insurance Group can help you confirm that your personal insurance still fits your current circumstances and the protection you expect.
Why a Year-End Insurance Review Is Important
Insurance should support the life you are living now, rather than the circumstances you had when you first purchased a policy. It is easy to put coverage in place and assume it will remain appropriate indefinitely. In reality, life can change quickly, while insurance details may stay the same unless they are updated.
As time passes, you may accumulate more property, take on additional financial responsibilities, or experience changes within your household. If your policies have not kept pace, the limits and protections you selected previously may no longer reflect your needs.
The final portion of the year is a practical time to revisit homeowners insurance, auto insurance, life insurance, disability coverage, and umbrella policies. A review can help ensure each policy continues to align with your current situation.
Buying a Home or Improving the One You Own
For many people, purchasing a home is among the largest financial decisions they will make. It is also a clear reason to take another look at insurance coverage.
If you purchased a property this year or completed substantial improvements to your current home, its rebuilding cost may be very different from before. Homeowners insurance should be based on the cost to repair or rebuild the property, not simply on its market value.
Projects such as a renovated kitchen, added living space, a finished basement, or an upgraded outdoor area can increase the level of coverage your home may require. Without a policy update, your existing protection may not accurately account for your home’s current value and features.
Adding a New Vehicle
A new vehicle can represent a meaningful increase in the value of the property you own. Even when it replaces an older car, it is important to make sure your auto insurance reflects the vehicle you now drive.
After a vehicle purchase, review your coverage limits, deductibles, and available optional protections. This matters especially when the new vehicle has a higher value or technology and features that could increase the cost of repairs.
A straightforward auto insurance review can help confirm that the policy is appropriate for the vehicle and consistent with your wider financial picture.
Life Changes at Home
Changes in your household are among the most frequent reasons personal insurance needs to be adjusted. A shift in family circumstances can affect several policies at once.
Marriage can mean shared property and new joint responsibilities. Divorce may call for revisions to policy information and coverage arrangements. Having a child may increase the need for financial protection, while a teen driver can change auto insurance considerations.
Other transitions deserve attention as well. A student leaving for college or an adult child returning home can create circumstances that should be reviewed across your insurance policies. These events are common, but their insurance implications are often missed.
Valuable Purchases and Meaningful Heirlooms
During a single year, it is common to acquire valuable belongings without considering how they would be covered after a loss. Those items can add up over time.
Jewelry, artwork, antiques, collectibles, and inherited family pieces may not be fully protected by a standard homeowners policy. If you have bought or received high-value items, it may be worth determining whether more protection is needed.
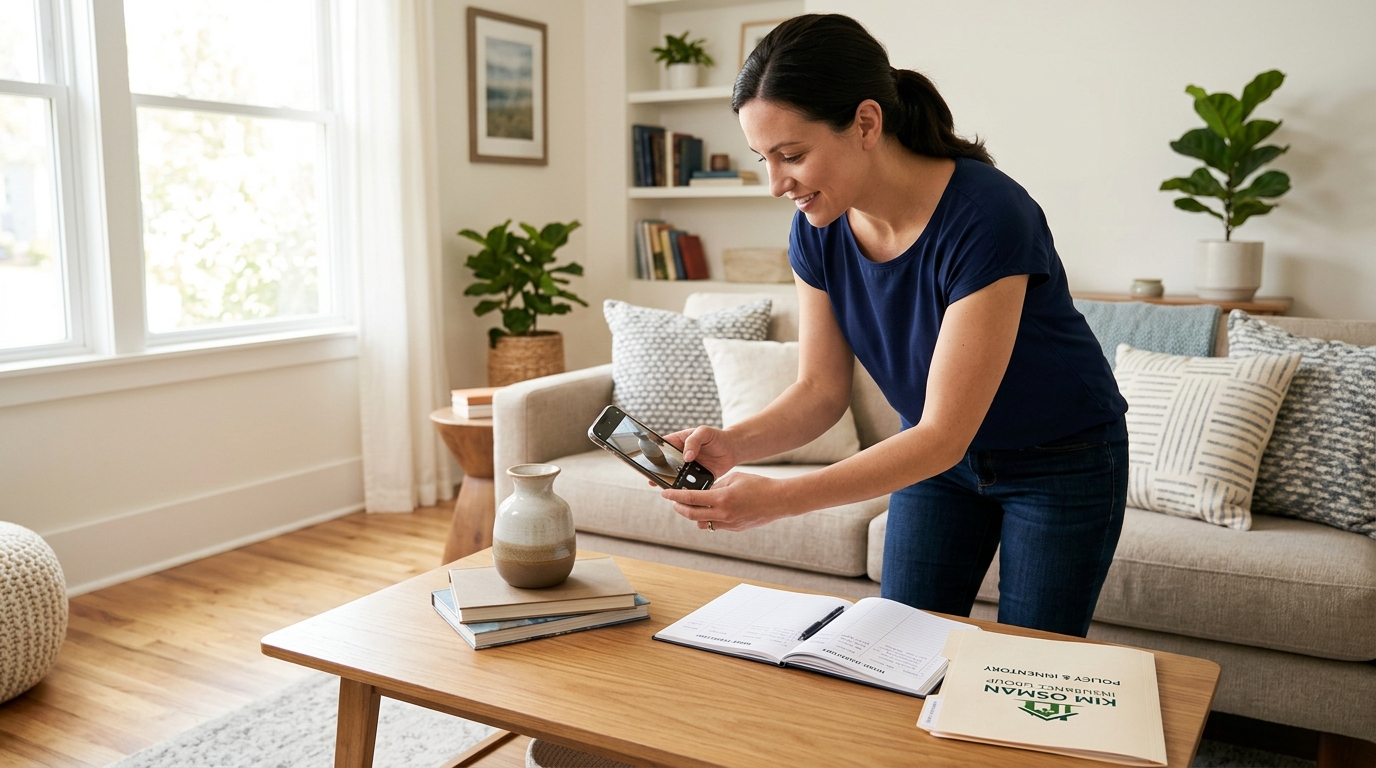
Creating an inventory of important possessions and reviewing it with an insurance professional can help you understand whether those belongings are properly protected from unexpected damage or loss.
Career Progress and Growing Financial Responsibilities
Professional achievements and financial progress are positive changes, yet they can also affect your insurance needs. As your resources and responsibilities grow, your potential financial exposure may change as well.
A promotion, a new position, a growing side business, an inheritance, or increased assets can all make a previous level of coverage less suitable. Protection that felt sufficient earlier may not provide the same confidence after your financial situation evolves.
These changes may be a reason to examine liability limits, life insurance, disability insurance, and umbrella insurance. Kim Osman Insurance Group can help you consider whether your coverage is evolving alongside your financial progress.
Use the Final 100 Days as a Planning Opportunity
The last 100 days of the year are a helpful reminder that insurance should not be treated as something to arrange once and ignore. Major changes often happen gradually, which can make it difficult to recognize just how different life has become over the course of the year.
If your life today does not look the same as it did at the beginning of the year, it is a good time to revisit your policies. A year-end review can help identify potential gaps, confirm that your coverage supports your goals, and provide greater confidence as you move into the new year.
If you have experienced meaningful changes this year, contact Kim Osman Insurance Group to schedule a coverage review. Our team is here to help your insurance keep pace with your life and the protection you may need next.